
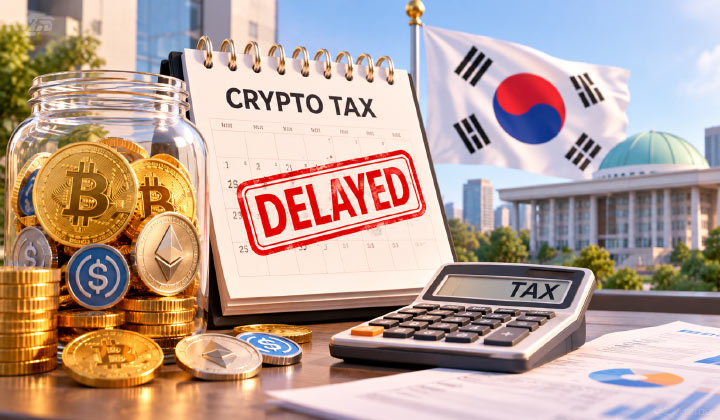
- South Korea is considering delaying its 22% crypto gains tax for a fourth time, pushing the effective date from January 2027 to potentially 2029.
- The tax applies to annual crypto profits above 2.5 million won (around $1,888), with a 20% income tax and 2% local levy.
- The presidential office reportedly favours a delay due to limited ability to monitor transactions on foreign exchange platforms.
- Democratic Party lawmaker Park Min-kyu has proposed tying implementation to South Korea’s full participation in the OECD’s Crypto-Asset Reporting Framework, which the U.S. joins in 2029.
South Korea is considering delaying gains taxes on cryptocurrencies once more. Local news reports citing the presidential office said policymakers were considering once again delaying the current 2027 start date for the tax to 2029.
NEW: South Korea is likely to postpone its cryptocurrency tax plan for the fourth time, according to a Newsis report.
The presidential office reportedly told local media that it is discussing delaying the tax, which is currently scheduled to take effect in January 2027.
The delay reportedly aims to align with the US timeline under the Crypto-Asset Reporting Framework (CARF), which the US is set to implement in 2029. CARF is the OECD’s international standard for bringing digital assets under global tax rules and enabling automatic exchange of transaction data between tax authorities.
— The Block (@TheBlockCo) October 26, 2026
Since 2020, the tax has been approved but delayed three times. It was first delayed to 2023 then to 2025, and most recently to 2027.
How The Tax Is Structured
The 22% levy consists of a 20% income tax and a 2% local tax, applying to annual cryptocurrency profits above 2.5 million won, equivalent to approximately $1,888.
Profits below that threshold are exempt. The structure mirrors how South Korea taxes certain financial instruments but would represent the first time the country formally taxes crypto gains at the individual level.
Why Another Delay Is Being Considered
A core concern is the government’s limited ability to monitor transactions on overseas crypto exchanges. Without reliable data on foreign platform activity, the tax could disadvantage South Korean exchanges and their users relative to peers trading internationally without domestic oversight. Lawmakers and the crypto industry have backed a delay, arguing the country’s compliance infrastructure is not ready.
OECD Reporting Framework As The New Condition
Democratic Party lawmaker Park Min-kyu proposed in October 2026 tying the tax’s implementation date to South Korea’s full participation in the OECD’s Crypto-Asset Reporting Framework (CARF).
Under the bill, the tax would take effect two years after the first exchange of crypto transaction data under CARF. The United States is set to join CARF in 2029, making that year the earliest practical implementation window for South Korea under the proposed bill.
Stay informed with the latest trends in Web3, blockchain innovation, and cybersecurity updates at 3verseTV
You need to login in order to Like



Leave a comment