
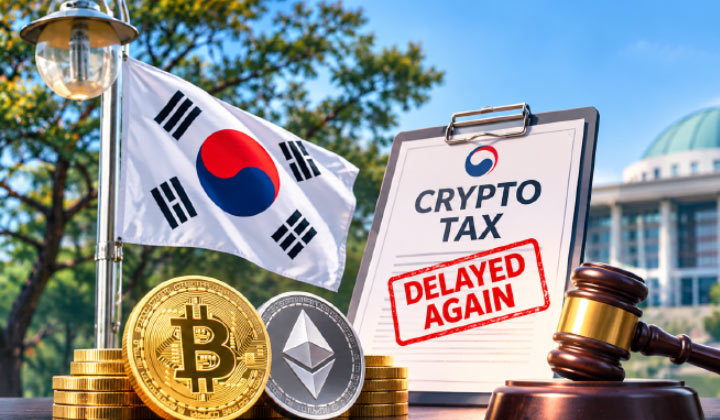
- South Korea’s ruling party has recommended a fourth delay to the cryptocurrency gains tax, pushing the deadline from January 2027 to approximately 2029.
- Party lawmakers cited the OECD’s international crypto tax data-sharing framework, which the US won’t join until 2029 and pending domestic digital asset legislation as key reasons.
- Finance Minister Lee Hyoung-il supports the January 2027 start date, while exchange group DAXA has advocated for the postponement.
- Under current law, annual crypto profits above 2.5 million won are taxed at 20% plus a 2% local levy; the tax was originally due in 2022.
A Fourth Postponement Proposed
The ruling party have proposed delaying the introduction of South Korea’s Much Awaited crypto capital gains tax for the fourth time.
Members of the ruling party in the Strategy and Finance committee of the National Assembly came to an agreement on November 3 to suggest introducing the tax in 2029 rather than January 2027. “While we agree that we should tax income, we cannot avoid having some lead time in the current policy,” said committee secretary Oh Gi-hyoung.
South Korea Considers Raising Crypto Exchanges’ Cold Wallet Requirement to 99% Following Binance Hack
According to News1, South Korea’s Financial Services Commission is considering raising the minimum cold wallet storage requirement for crypto exchanges from 80% to around 99% following the recent Binance hack. Upbit reportedly holds over 99% of customer assets in cold wallets, compared with roughly 94% at Bithumb and 85% at Coinone. Industry participants warn that stricter requirements could delay withdrawals and increase operational burdens, particularly for smaller exchanges. The proposal remains under discussion and has not been adopted.
— Wu Blockchain (@WuBlockchain) November 3, 2026
The tax has been scheduled for 2022 but has now been delayed three times. It taxes individuals making more than 2.5 million Korean Won in virtual asset profits in the course of a year at 20% (plus 2% local tax).
Why The Delay & What Changes
The ruling party have stated the following reasons for delaying: Firstly, there is an international cryptocurrency tax reporting system which is set to go ahead in 2029 (widely known as the OECD Crypto-Asset Reporting Framework). The U.S only joins this system in 2029. To achieve alignment between the domestic tax system and the international system will make enforcing the system easier.
Secondly, South Korea’s General Act on Digital Assets which will lay down regulations for stablecoin and exchange are set to go through in the first half of 2027. Finally they want the National Tax Service and exchanges to trial the data sharing processes and simulate the tax process using real data.
Divided Views On The Tax Timeline
There is a clear split in the South Korean government. The Finance Minister, Lee Hyoung-il has publicly stated that the tax should be introduced as scheduled in January 2027. He stated that delaying any further will damage the credibility of the tax and cause uncertainty for investors and exchanges.
However, the Digital Asset Exchange Alliance (DAXA) who represent South Korea’s largest crypto trading platforms have advocated for a delay. This aligns with the ruling party suggestions. The suggestion will be considered by the Tax subcommittee of the National Assembly when discussing amending the Income Tax Act. A decision will likely be made before the end of the year.
Stay informed with the latest trends in Web3, blockchain innovation, and cybersecurity updates at 3verseTV
You need to login in order to Like



Leave a comment