
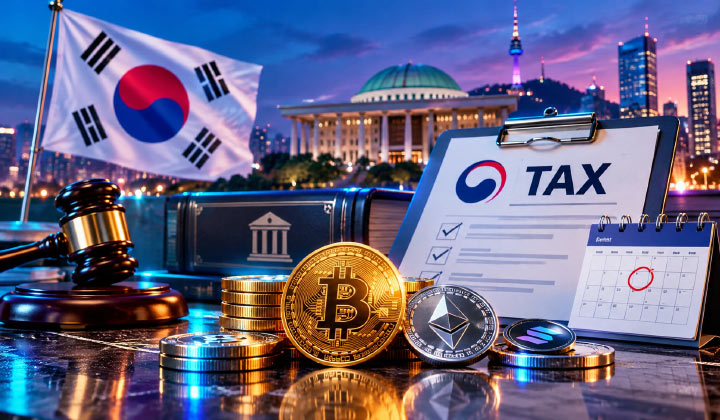
South Korea’s National Tax Service (NTS) will issue comprehensive cryptocurrency tax guidelines in November 2026, in preparation for a 22% tax rate of qualifying gains in digital assets beginning on January 1, 2027. The guidance is expected to provide clarification on how taxes will be calculated on crypto activities such as staking rewards, airdrops, hard forks and decentralized finance (DeFi). The tax authorities are consulting cryptography exchanges and the nation’s finance ministry in preparation for the proposed changes.
NEW: South Korea is preparing to issue crypto tax guidelines next month, ahead of the planned implementation in January 2027, according to Yonhap.
Local traders have been petitioning for a delay, citing lack of clarity and infrastructure. https://t.co/IYFOUzNhfb
— The Block (@TheBlockCo) October 14, 2026
NTS Commissioner Lim Gwang-hyeon gave the news of the preparations in a parliamentary audit on October 13, after legislators questioned the nation’s officials on whether different forms of crypto-income have been clearly outlined.
The issue is significant as not all forms of cryptocurrency gains derive from purchasing and selling digital assets. Investors may also earn staking rewards for participating in blockchain networks, obtain tokens as a reward for participating in airdrops or receive new assets as part of a hard fork. These various activities represent different financial structures and may require clarification for taxation purposes.
Lim said the tax authority would focus on the economic nature of the activity. Some activities involve transferring or lending digital assets, while others may need further clarification from the Ministry of Finance and Economy. The final guidelines have yet to be made available and the tax authorities have not confirmed if the proposed release in November will address all outstanding issues.
In accordance with the system that the tax authority has proposed, qualifying cryptocurrency incomes will be taxed as unique other income. This combined rate of 22% would entail a 20% national tax and an additional 2% local income tax. An annual basic deduction of 2.5 million won will apply. Qualifying acquisition costs and expenses in transactions will also be taken into account when assessing taxable gains.
South Korea has deferred the introduction of its cryptocurrency tax multiple times since lawmakers approved the framework back in 2020. The start of implementation was moved from 2022 to 2023, before then being moved to 2025 before another two-year delay was approved in December 2024.
The deadline of January 2027 still stands, although some legislators and industry representatives continue to question whether another delay should be considered or whether the tax should be eliminated altogether.
The tax authorities are also working to obtain more transaction information on domestic exchanges while challenging the collection of all transactions through overseas exchanges and private wallets. International mechanisms for exchanging information may be of help, but it will not capture all transactions.
Given the current schedule, it will be investors who will complete filings of qualifying gains earned in 2027 beginning in May 2028. The planned November guidelines will prove significant in helping investors understand what they owe in taxes prior to the tax taking effect.
Stay informed with the latest trends in Web3, blockchain innovation, and cybersecurity updates at 3verseTV
You need to login in order to Like



Leave a comment